Debt Payoff Planner: Tracker
Debt snowball vs. debt avalanche
Two ways to choose where your extra payment goes. Compare the order, time and estimated interest.

Snowball: smallest balance first
Pay the regular amount on each debt. Direct extra money to the smallest balance. Closing a smaller debt sooner can help you keep going.

Avalanche: highest interest first
Pay the regular amount on each debt. Direct extra money to the debt with the highest annual interest rate. This targets the more expensive debt first. Compare the actual estimates for your payment amounts.
A worked example
Three debts: Credit card — $3,250 at 24.99% ($95/month); Car loan — $8,400 at 6.5% ($210/month); Medical bill — $640 at 0% ($25/month). The two payoff strategies add $150 per month. All example amounts are in USD.
| Method | Months | Estimated interest |
|---|---|---|
| Regular payments only | 61 | $3,587.67 |
| Highest interest first | 29 | $1,427.12 |
| Smallest balance first | 30 | $1,618.61 |
The regular-payments baseline keeps each debt’s own monthly payment, with no extra payment or transfer of freed payments. Both payoff strategies add $150 per month and transfer freed regular payments from the following month. Unused final-payment money is not reallocated in the same month.
Open calculator
Keep going in the app
A plan is a start. Every payment is progress.
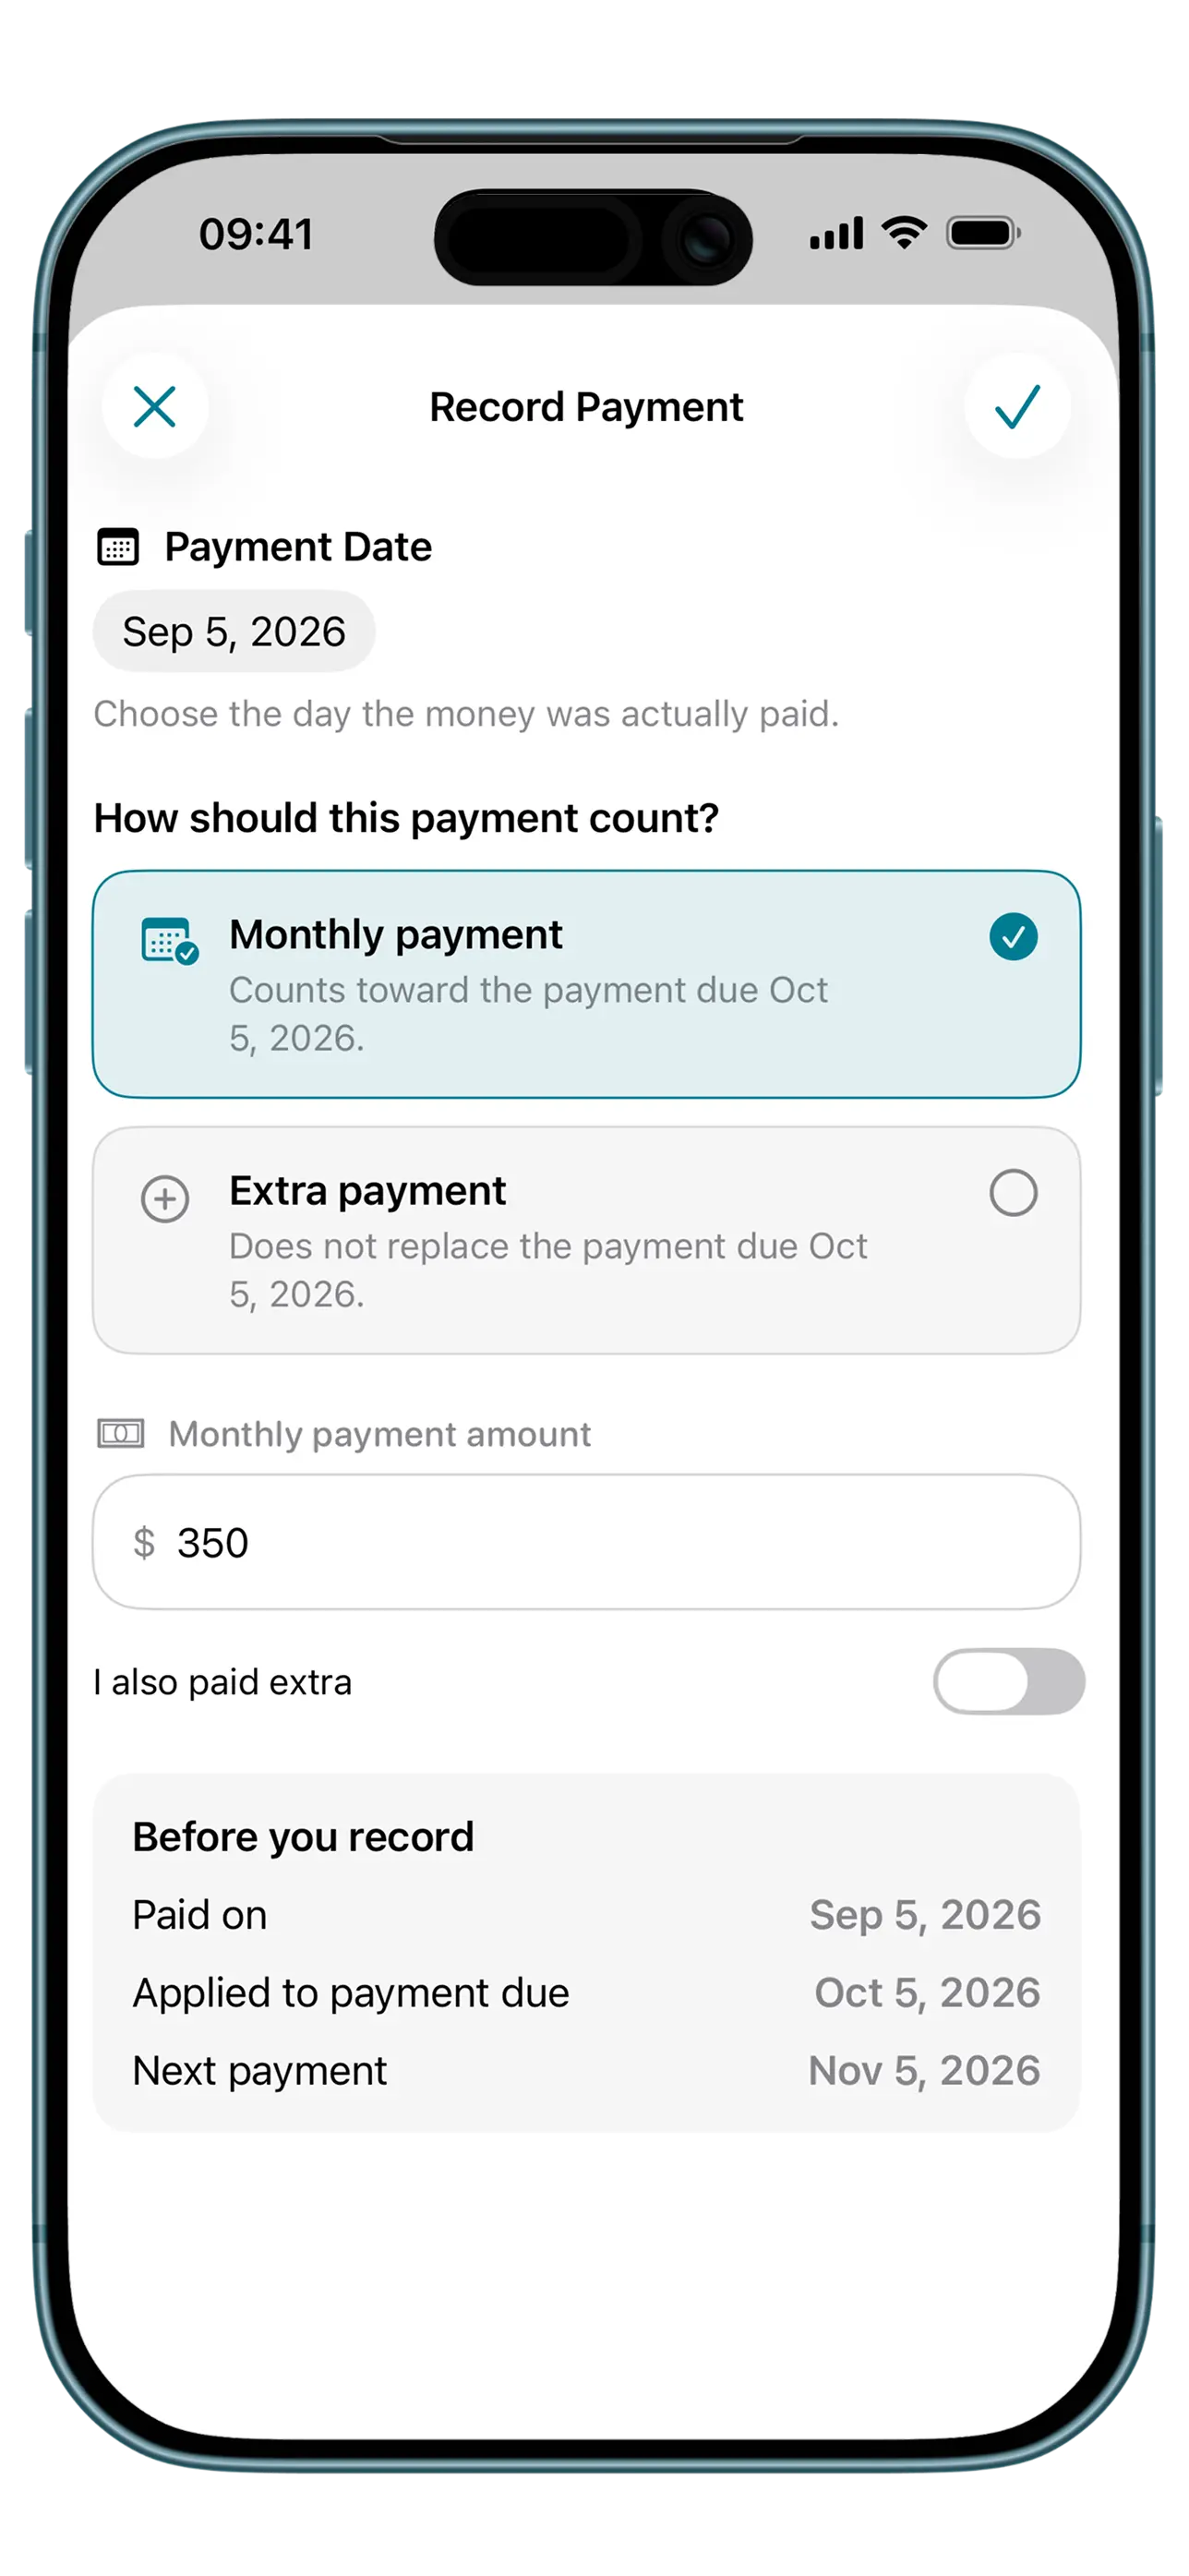
Debt Payoff Planner brings debts, payment history, reminders, payoff strategies and progress reports together on your iPhone.