Free printable debt free chart for any amount
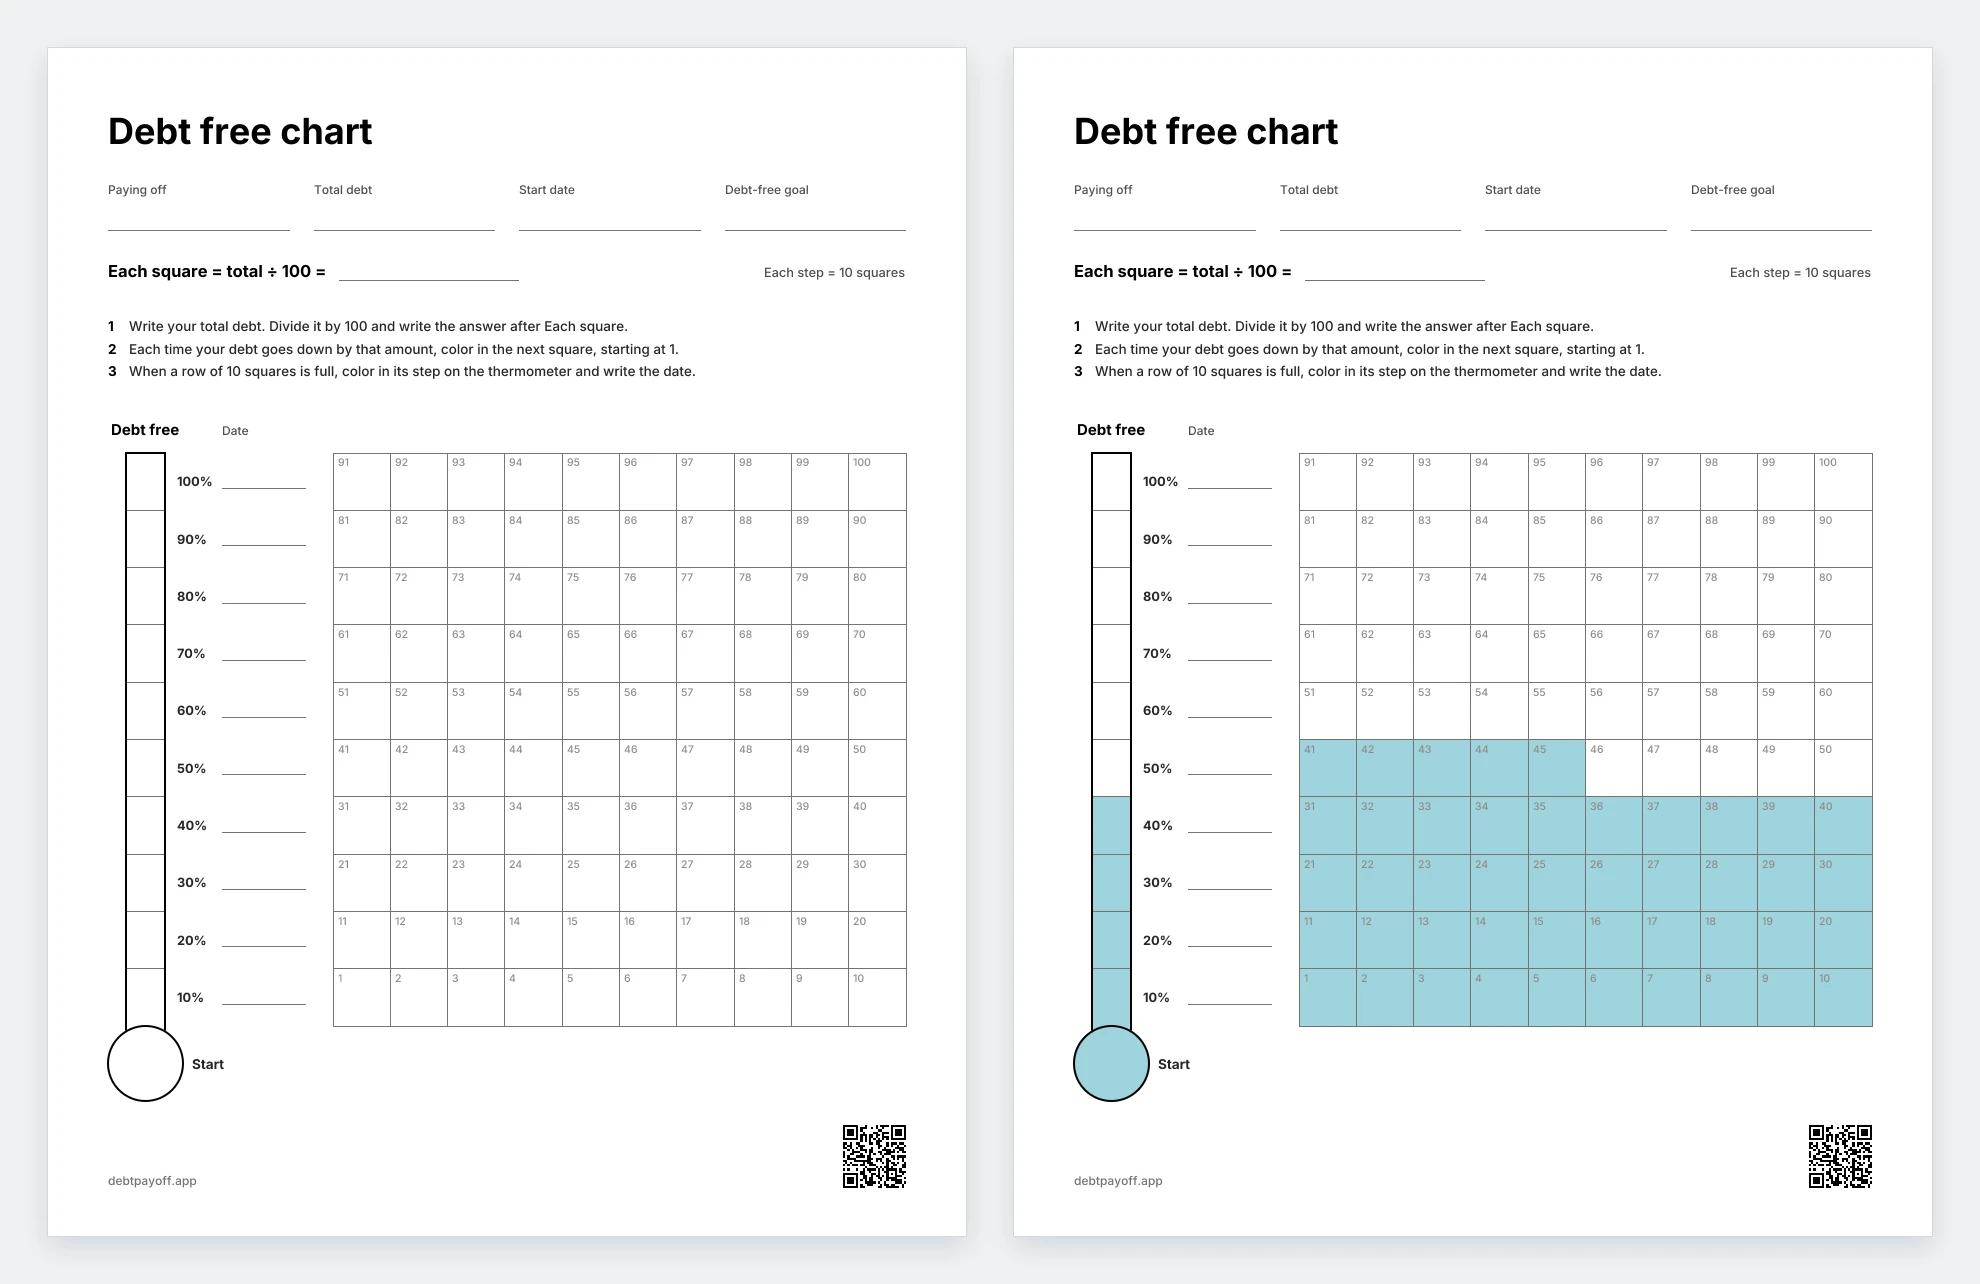
A debt free chart is a page you color in as your debt goes down, so you can see how far you have come. This free printable puts a thermometer and 100 numbered squares on one page. Each square is your total debt divided by 100, so the same chart works for any amount.
- Free, no email
- US Letter and A4
- Works for any amount
 Free, no email
Download the debt free chart
 US Letter PDF (59 KB)
US Letter is the usual paper size in the US and Canada. A4 is the usual size in most other countries. Both files have the same page.
- Page
- One page with a thermometer of 10 steps and 100 numbered squares
- Each square
- Your total debt divided by 100. You write the amount on the sheet.
- Each step
- 10 squares, or 10% of your debt, with a line for the date
- Paper
- US Letter (8.5 × 11 in) and A4 (210 × 297 mm)
- Ink
- Black and gray lines on white, with no color fills
- Currency
- Any. The sheet has no currency signs.
What the chart looks like
How to use the debt free chart
- Write your total Add up what you owe on the debts you want to pay off and write it in Total debt. It can be one credit card or all your debts together.
- Work out each square Divide the total by 100 and write the answer after Each square. On $10,000 of debt, each square is $100.
- Color in a square Check your balance after each payment. Each time it goes down by the amount of one square, color in the next square. Start with square 1 at the bottom left and work up. If it went down by more, color in more than one.
- Fill the thermometer When a row of 10 squares is full, you have paid off another 10%. Color in that step of the thermometer and write the date next to it.
- Keep it where you see it Put the chart on the fridge or next to your bills. When square 100 is colored in, the debt is paid off.
How long it takes to color in the whole chart
The chart is full when the debt is paid off. The table shows how many months that takes at a 22% APR, with the same payment every month.
| Total debt | Each square | $300 a month | $500 a month |
|---|---|---|---|
| $5,000 | $50 | 21 months $1,022 interest | 12 months $574 interest |
| $10,000 | $100 | 52 months $5,596 interest | 26 months $2,571 interest |
| $20,000 | $200 | Never $366.67 interest in month 1 | 73 months $16,378 interest |
The table assumes the APR stays the same, you add no new charges and you pay no fees. Interest is the balance times the APR divided by 12, rounded to the cent each month.
At $300 a month, $20,000 at 22% is never paid off. The first month’s interest is $366.67. That is more than the payment, so the balance never goes down and you would never color in a square. The debt payoff calculator shows the same warning. At $500 a month, the chart is full in 73 months.
The squares go faster as you pay
The first row takes the longest. Early on, more of each payment goes to interest. As the balance goes down, less goes to interest and more goes to the debt. On $10,000 at 22% and $300 a month, the first 10 squares take 9 months and the last 10 take 3.
On $20,000 at $500 a month, the first row takes 14 months and the last row takes 4. So a slow start is normal. The chart fills up faster as you go.
| Thermometer step | Squares | $10,000 $300 a month | $20,000 $500 a month |
|---|---|---|---|
| 10% | 1 to 10 | 9 | 14 |
| 20% | 11 to 20 | 7 | 11 |
| 30% | 21 to 30 | 6 | 9 |
| 40% | 31 to 40 | 5 | 7 |
| 50% | 41 to 50 | 5 | 7 |
| 60% | 51 to 60 | 5 | 6 |
| 70% | 61 to 70 | 4 | 6 |
| 80% | 71 to 80 | 4 | 5 |
| 90% | 81 to 90 | 4 | 4 |
| 100% | 91 to 100 | 3 | 4 |
Debt free chart or debt snowball printable?
This chart tracks one number, your total. It has no list of debts and no monthly log. The debt snowball printable lists up to 10 debts from the smallest balance to the largest and logs 24 months of payments. Use the snowball printable to plan which debt to pay first. Use this chart to watch the total go down. You can use both at the same time.
Find out when the chart will be full
The chart does not calculate anything. To see when you will color in the last square, enter your debts in the free debt payoff calculator. It shows your debt-free date and the payment for every month. The $10,000 example opens $10,000 at 22% with $300 a month, which takes 52 months. Write your own debt-free month in the Debt-free goal field.
Track the payoff on iPhone
Debt Payoff Planner: Tracker is an iPhone app for paying off debt with the snowball or avalanche method. You type in your debts, and it plans the payoff and records each payment. It is free for up to 3 debts, with no account and no bank link. See it on the App Store.
Questions
All questions
Is the debt free chart free?
Yes. Both PDFs download from this page. There is no sign-up, no email and no account.
How does one debt free chart work for any amount?
Each square is your total debt divided by 100. You write that amount on the sheet. On $10,000 each square is $100, and on $20,000 each square is $200. The chart always has 100 squares.
How do I fill in the debt thermometer?
Each step of the thermometer is 10 squares, or 10% of your debt. When a row of 10 squares is full, color in the step next to it and write the date on its line.
Can I use one chart for several debts?
Yes. Add up the balances and write the total. You can also print one chart for each debt. To list your debts and the order to pay them in, use the debt snowball printable.
What if my balance goes up?
Keep the squares you have colored in. Color the next square once the balance is below that mark again. New charges and fees make the chart fill up more slowly.
Should I print US Letter or A4?
Pick the paper in your printer. US Letter is the usual size in the US and Canada. A4 is the usual size in most other countries. Both files have the same page.
Does it print in black and white?
Yes. The page uses only black and gray lines and text on white paper. You can color it in with any pen or pencil.
When to talk to someone
- If your payments take more than you can cover each month, a nonprofit credit counselor can go through your budget and your debts with you. The Consumer Financial Protection Bureau says credit counseling can be free or low cost, and that counselors may charge for some services. It points to the National Foundation for Credit Counseling (nfcc.org, 877-360-6322) and the Financial Counseling Association of America (fcaa.org). Get any fee in writing before you sign up.
- If a debt collector or your card issuer treats you unfairly, you can submit a complaint to the CFPB at consumerfinance.gov/complaint or (855) 411-2372, Monday to Friday, 9 a.m. to 6 p.m. ET.
- If a company wants a fee before it settles any of your debts, the FTC calls that a warning sign. You can report it at ReportFraud.ftc.gov.
- If you are sued over a debt and your income is low, a legal aid office may help for free. Find the one near you at lsc.gov.
- If money worries leave you in crisis, call or text 988 to reach the 988 Suicide & Crisis Lifeline. It is free, confidential and open 24/7. In an emergency, call 911.
Outside the US, look for a free debt advice service run or approved by your government.
Read next
All guides- Debt snowball printable (free PDF) A two-page tracker in US Letter and A4. List 10 debts, log 24 months and color in 50 boxes.
- Debt payoff calculator Compare the snowball and avalanche methods with your balances, interest rates and monthly payments.
- How long to pay off $10,000 of card debt Months and interest at 4 APRs and 5 monthly payments, and the payment for each payoff time.


